Non bank lending specialists since 1999
Where you go when your bank saysNO!™
Declined for self employed income, bad credit or IRD arrears? We're licensed financial advisers who know New Zealand's non bank lenders, and how to find you a yes.
7 declines elsewhere. Approved in 24 hours with us.A recent NonBank client
Pioneers of non bank lending in New Zealand.
Recognised by the New Zealand Mortgage Awards and Avanti Finance.
Advice across 25 bank and non bank lenders, including
- Avanti
- Basecorp
- Bluestone
- Cressida
- First Mortgage Trust
- Heartland
- Liberty
- Pepper Money
- Plus Finance
- Resimac
- Southern Cross
- Prospa
- ASAP
- SBS
- ASB
- ANZ
- BNZ
- Westpac
What did your bank say no to?
Pick the closest match. Your adviser will look at the whole picture, not just the box a bank's computer ticked.
Home loans
First homes, bad credit, refinancing and new builds.
Self employed & low doc
When your financials aren't up to date.
Second mortgages
Release equity for business, IRD arrears or debt consolidation.
Commercial & rural
Investment, development, owner-occupied and farm finance.
Business loans
Short-term funding, with money available within 24 hours.
Bridging finance
Buy before you sell, or stop a mortgagee sale.
- Self employed
- Bad credit
- IRD arrears
- Mortgagee sales
- Debt consolidation
- Buy before you sell
- Rural & farms
- Development
- Kiwis overseas
Self employed & low doc
No up-to-date financials? You can still borrow.
Business owners, contractors and commission earners often get turned away because their accounts are behind. Low doc lenders look at the bigger picture.
- Buy a home or refinance with low doc
- Release equity to grow your business
- Clear IRD arrears with a second mortgage
Commercial & rural
Farms, developments and commercial property.
When the bank wants out, or won't come in, we arrange finance to buy or refinance rural land, fund a build, or invest in commercial property.
- Rural and farm loans
- Development and construction finance
- Commercial and rental investment
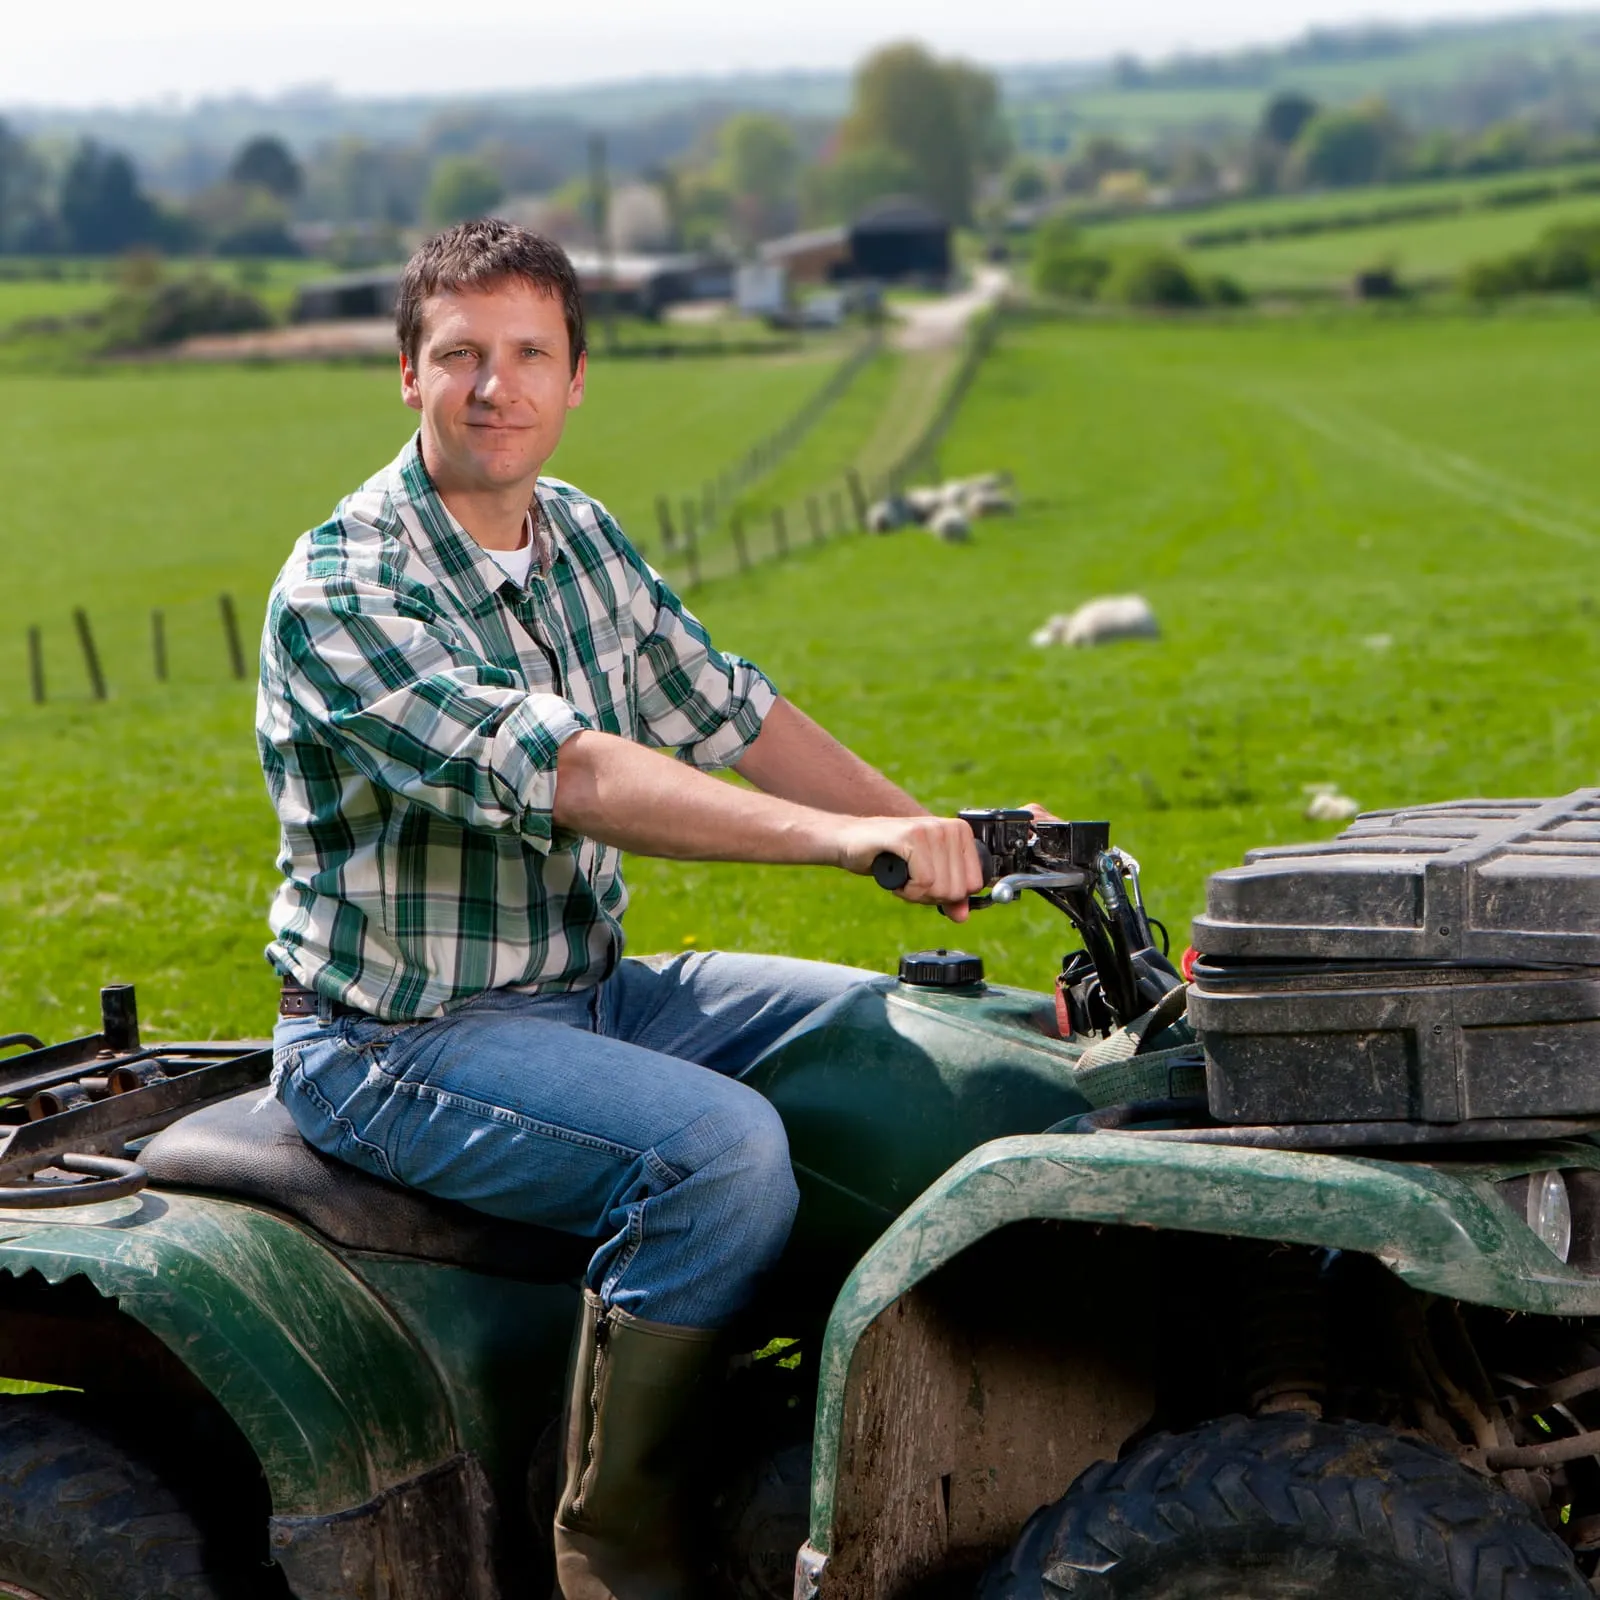
How we find you a yes.
Tell us what happened.
Call or send a quick enquiry. Declined, in arrears, no financials: we've heard it all, and none of it is a dead end.
We take it to the right lenders.
Your adviser matches your situation to lenders on our panel, presents your case and negotiates the terms.
Settle, then plan your way back.
We keep in touch after settlement, and when your finances are back on track we'll help you return to a bank.
Why use an adviser
How we stack up.
A bank can only offer its own loans, and going direct means one lender at a time. We compare the market for you, and our advice costs you nothing.
Lending criteria, fees and terms vary by lender.
| NonBank | Your bank | Going direct | |
|---|---|---|---|
| Lenders compared | 25 on our panel | One: theirs | One at a time |
| Self employed, no current financials | Low doc options | Often declined | Varies |
| Past credit issues or arrears | Considered case by case | Often declined | Varies |
| Cost of advice | No fee | No advice given | No advice given |
Reviews
Turned away by the banks. Sorted by us.
Real stories from Kiwis who came to us after hearing no, sometimes more than once.
Read all reviewsAllan Nicol, he is an awesome advisor. Very helpful, prompt and efficient person. We had been rejected quite a few times by almost all the banks and most of the brokers until I met Allan from First Rate Mortgages. Now that Allan has made our dream come true, we have bought our very first home. We managed to work through in this desperate time of Covid-19 and am glad we made it through. We highly recommend Allan and First Rate Mortgages. We are really pleased with the service and will continue to work with Allan in future.
 Manjeeta, first home buyerAdviser: Allan Nicol
“A great company to deal with - Natalie was so helpful, gave us a range of options and delivered fantastic customer service – can’t fault them!”
“Kim has organised finance for us on a few occasions and has managed to get us very competitive rates despite us falling outside of the criteria most of the banks require. Kim has always been extremely helpful and I would definitely recommend his services; in fact I already have.”
“I am so completely impressed with the whole lending process, how quickly everything was done and monies paid out immediately. Danielle made the whole process so easy taking all the stress out of it for me. She kept in constant contact and was positive and uplifting the whole way through. I’m 100% impressed and would return for further help in future. Thank you so much!”
“What truly set Murray apart was his willingness to go to the extra mile. He was incredibly responsive, often answering our emails and calls outside of regular business hours. Murray meticulously followed up on every detail, ensuring that our application process was smooth and stress-free.”
Meet your advisers.
Licensed financial advisers, most of whom spent years inside the banks before joining us. You'll deal with the same person from first call to settlement.
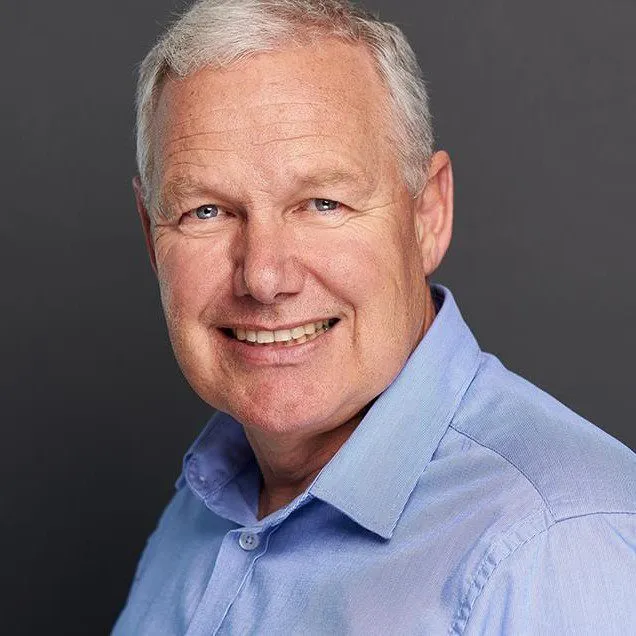
Kim Lyons
Director, financial adviser
Former ANZ mobile home loans manager. Now leads one of NZ's most experienced non bank teams.
Allan Nicol
East & South Auckland
Buying, refinancing and consolidating debt. A Flat Bush local for nearly 20 years.
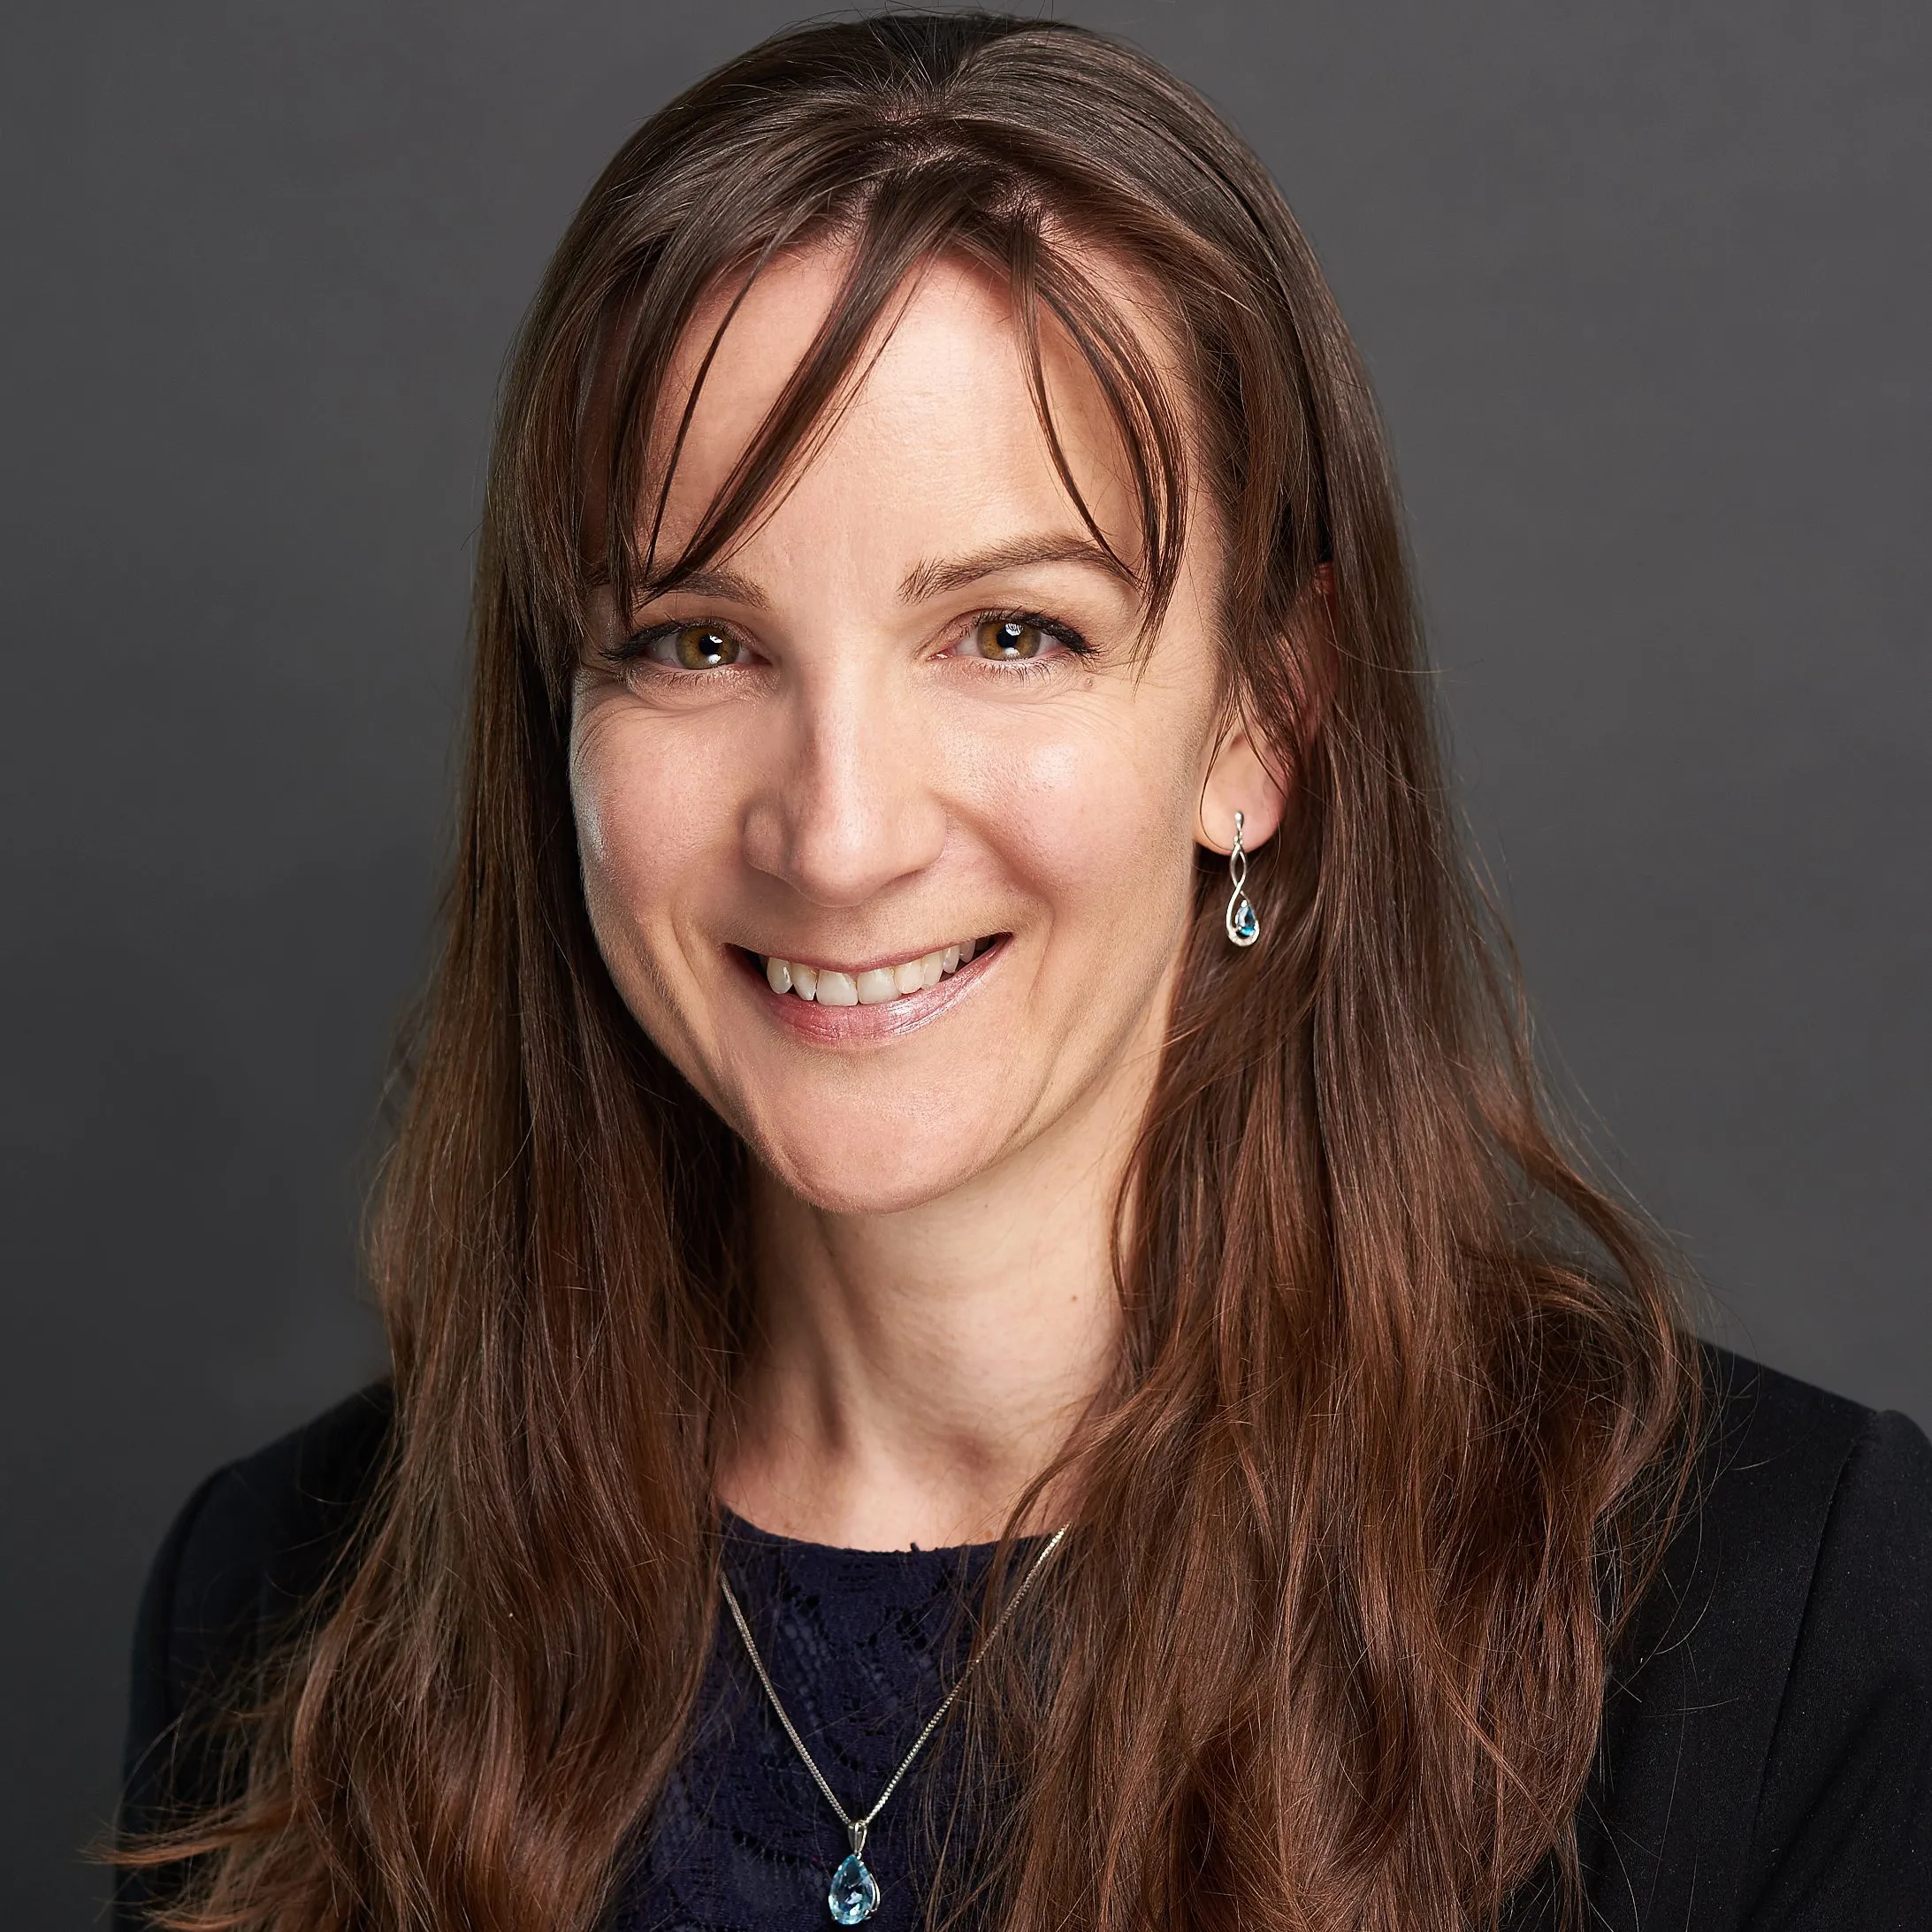
Danielle Happy
Construction & commercial
Development, subdivision and the “outside the box” deals other lenders pass on.
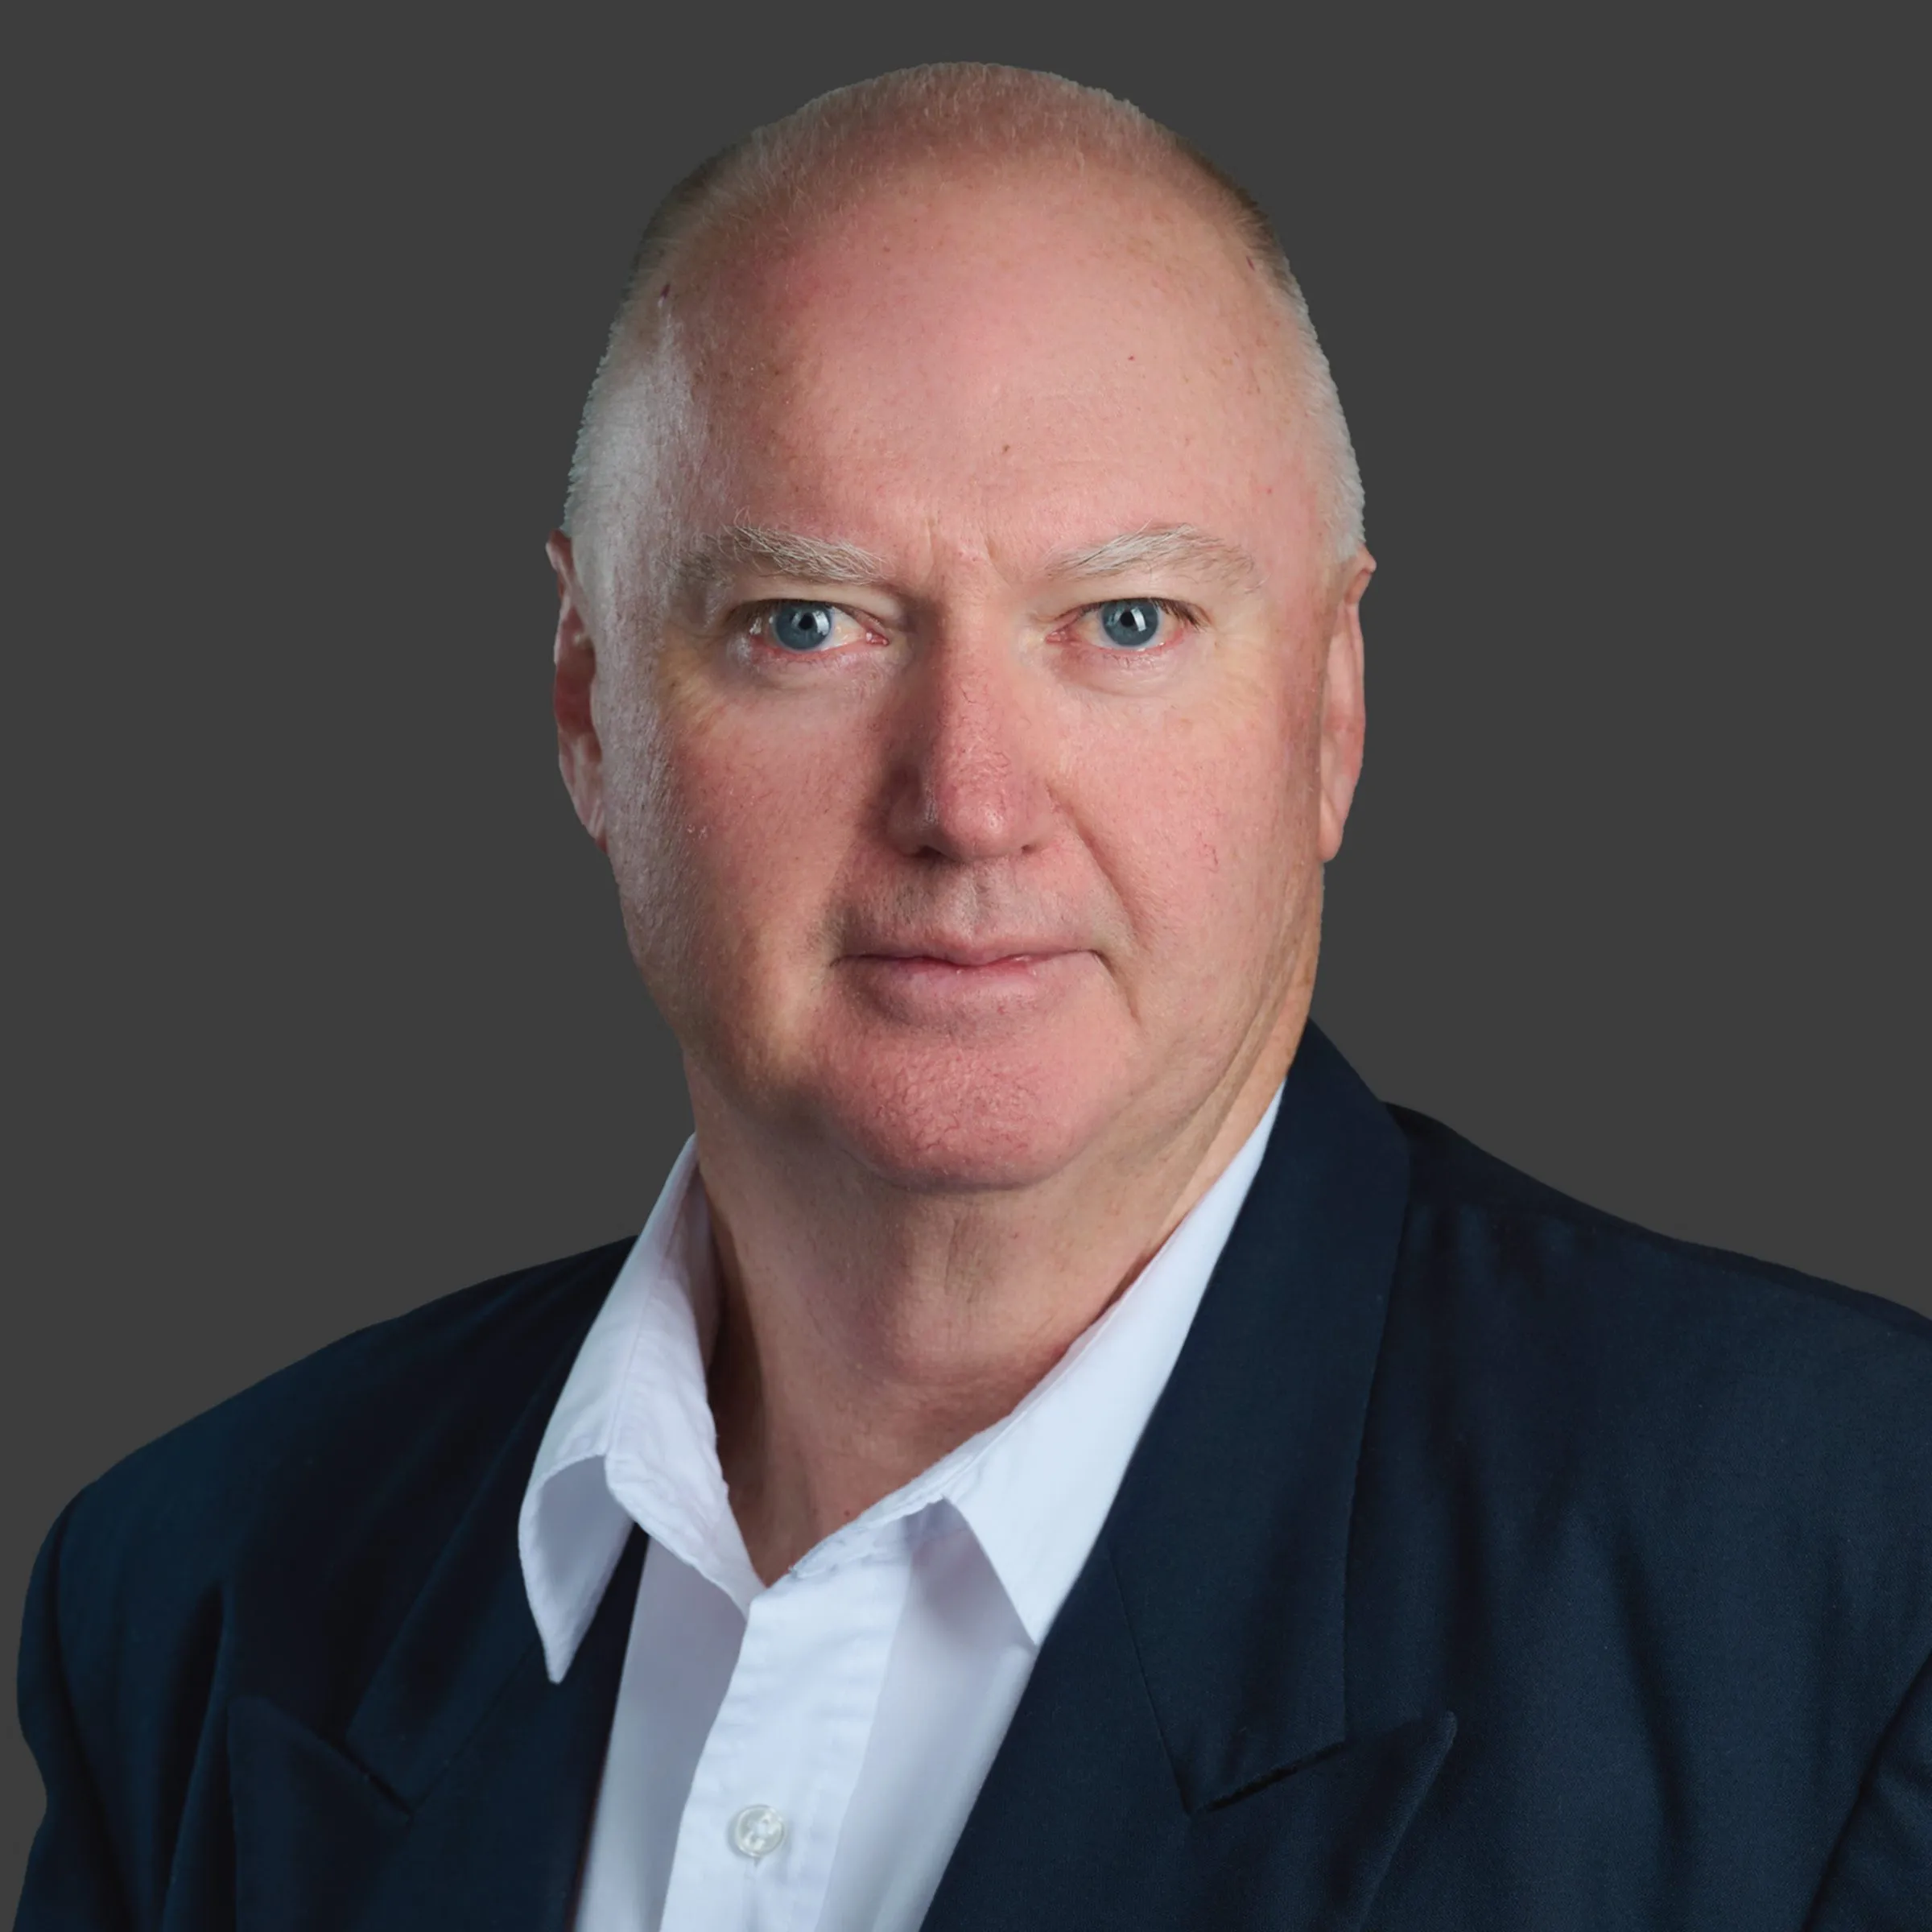
Murray Moore
Commercial & rural
Commercial property, first home buyers, new builds and rural loans.
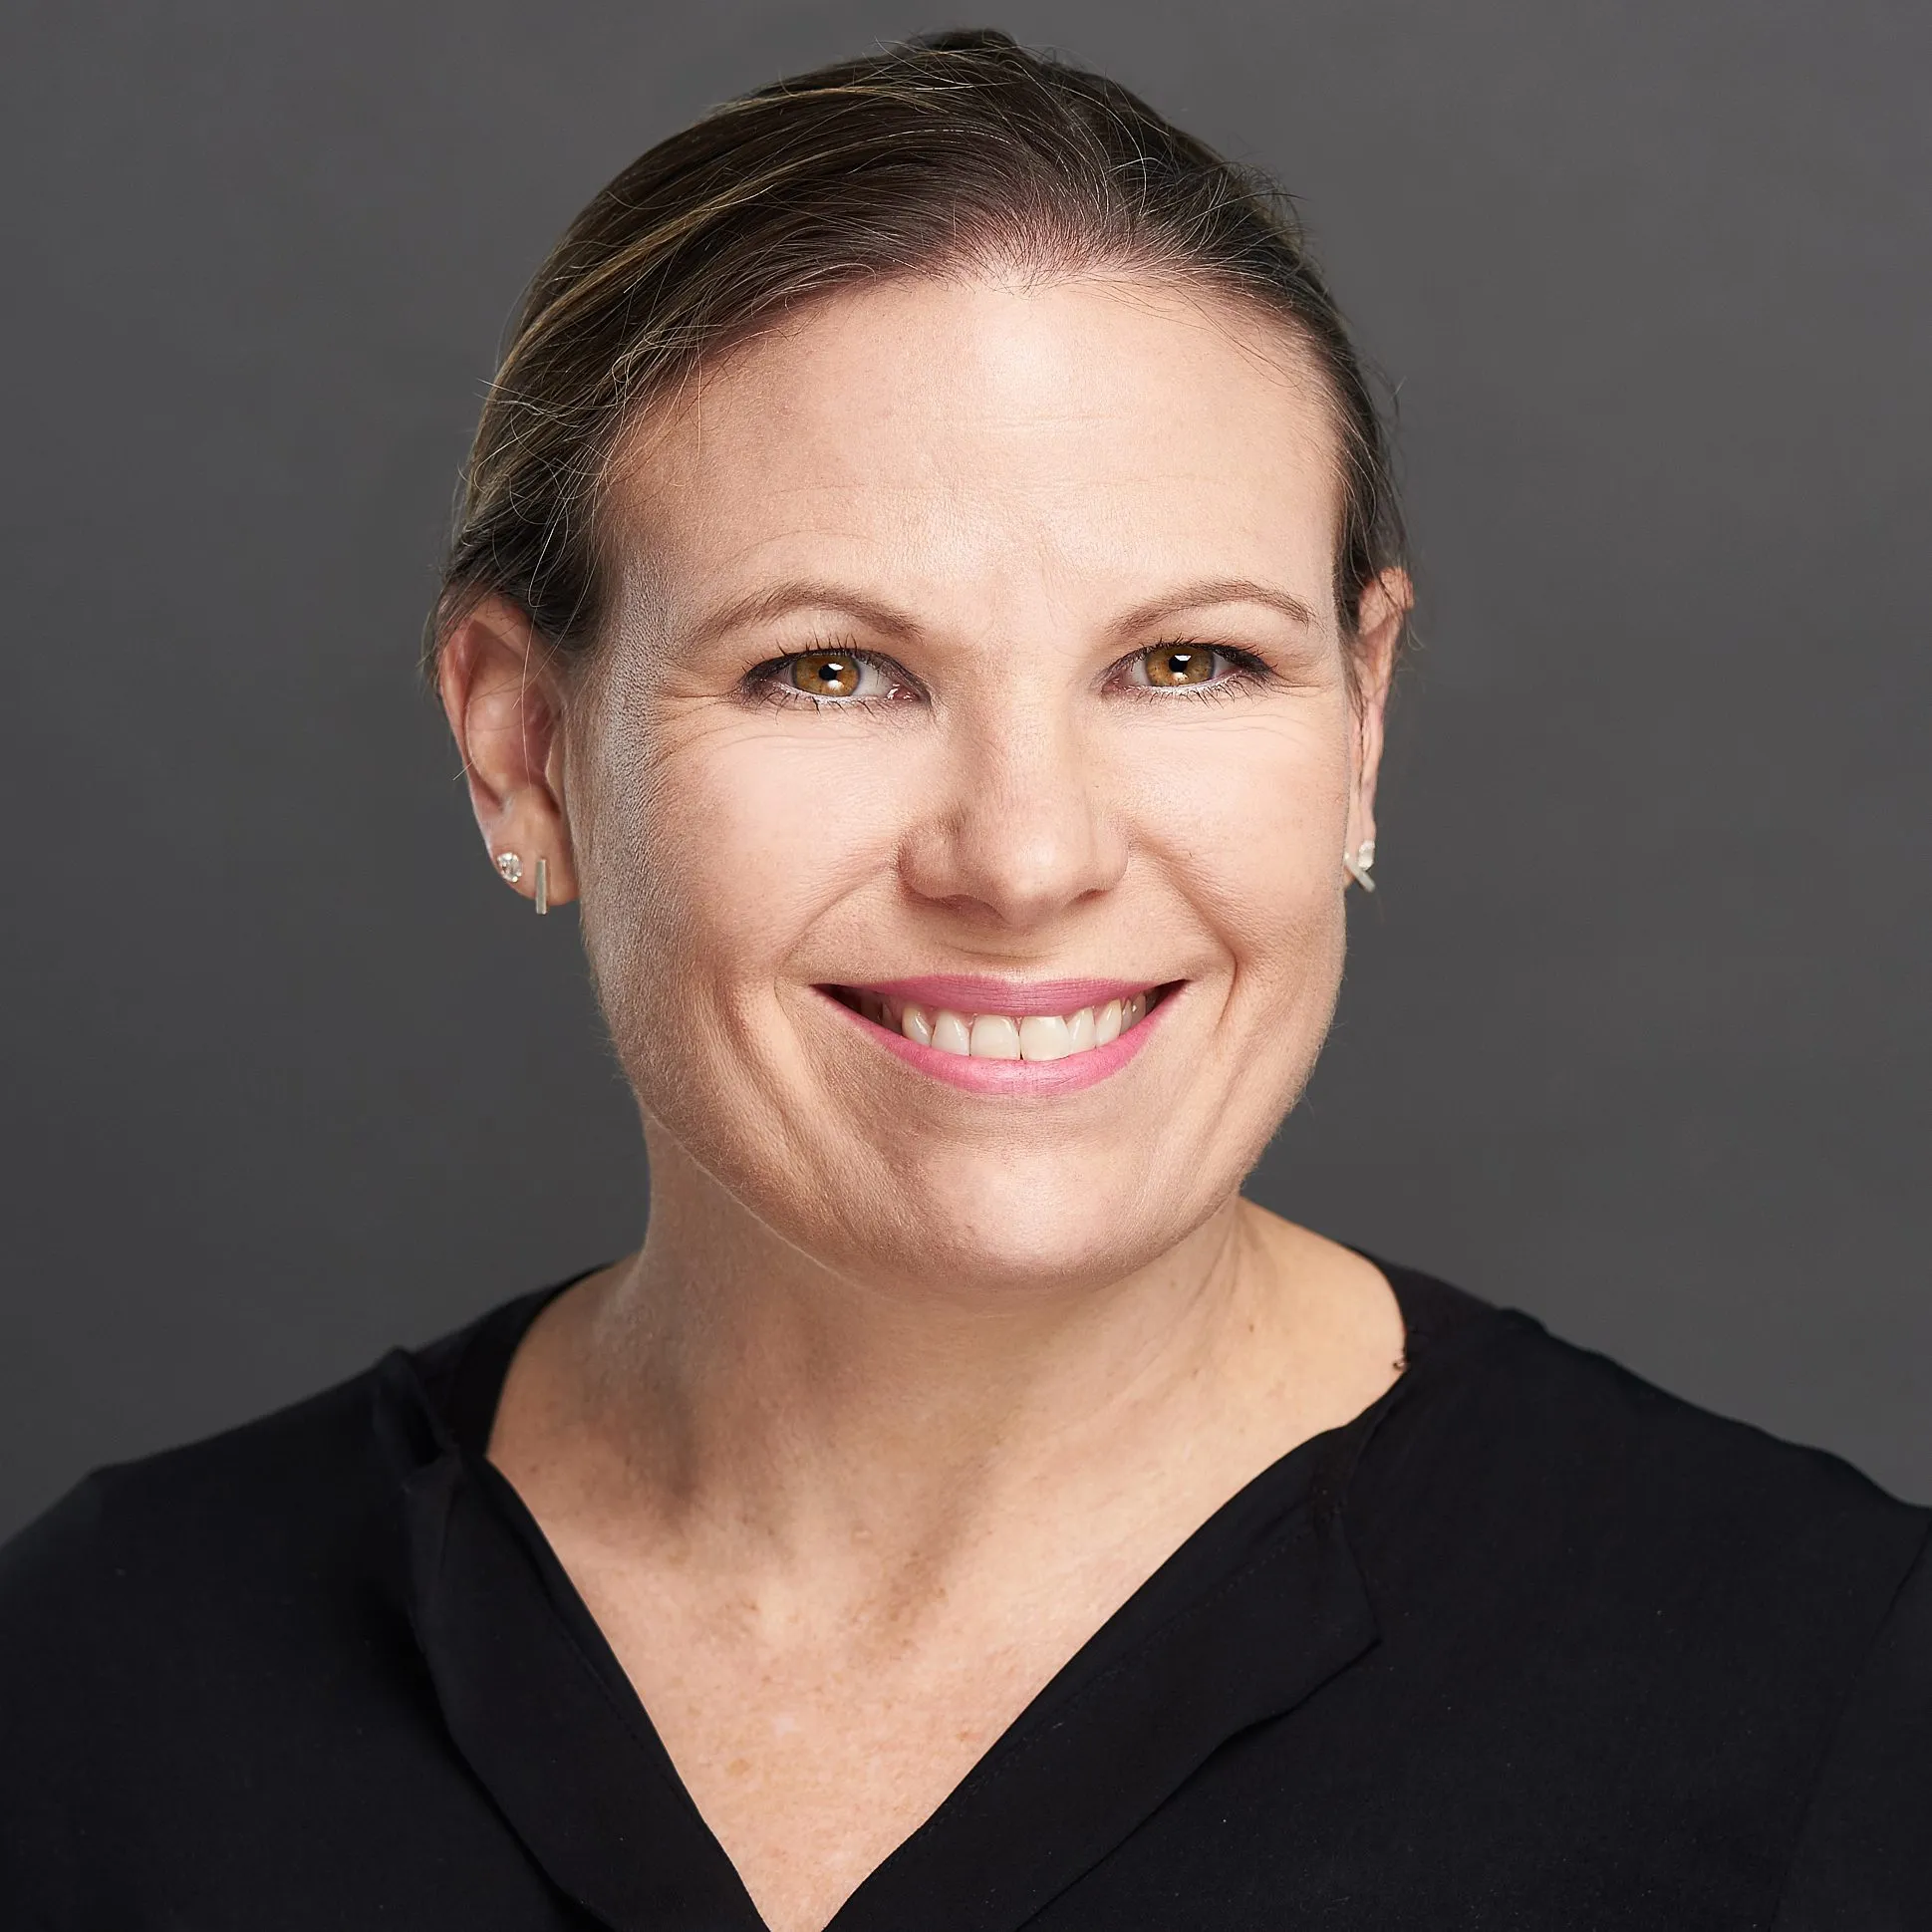
Natalie Siebrits
Home loans
14 years at Sovereign Home Loans before joining the team in 2015.
Answer
What is a non bank lender?
A lender that isn't a registered bank, sometimes called a second tier lender. They set their own lending criteria, so they can often help when a bank's rules say no: self employed income, past credit issues, unusual properties or short-term needs.
Will a non bank loan cost more than a bank loan?
Usually the interest rate is higher, and some lenders charge fees. That's why we compare options across our panel and plan with you how to move back to a bank once your situation allows.
Do you charge for your advice?
No. There's no fee for our advice. Lenders pay us a commission when your loan settles, and our disclosure statement explains exactly how that works.
Can I borrow if I'm self employed without up-to-date financials?
Often, yes. Low doc lenders can accept other evidence of income, such as bank statements, GST returns or a letter from your accountant.
Can you help if I'm behind with IRD or facing a mortgagee sale?
Yes. A second mortgage or short-term finance can clear IRD arrears or buy you time to sell or refinance. The sooner you call, the more options you'll have.
Bank said no? Let's find your yes.
Talk to a licensed financial adviser today. There's no fee for our advice.